When a Normal Payment Looks Suspicious
AI fraud in banking is helping financial institutions identify suspicious transactions by analyzing patterns in customer payment activity. Every day, banks process thousands of transactions, and not all unusual activity is necessarily fraudulent. A sudden high-value payment, multiple transfers within a short period, or a transaction from an unfamiliar location may raise a warning.
Machine learning models help banks examine these patterns, compare them with historical transaction behavior, and flag activities that may require further investigation. Instead of relying only on fixed rules, these systems can identify complex patterns that might otherwise go unnoticed.
However, AI does not automatically know whether a transaction is genuinely fraudulent. It can flag legitimate payments as suspicious, miss new fraud techniques, or produce alerts that require human verification. This creates an important question: How effective is machine learning at detecting banking fraud, and where does it fall short?
Let's understand how these systems work, what information they analyze, why false positives occur, and why human review remains an essential part of fraud detection.
1. What Is AI Fraud Detection in Banking?
AI fraud detection in banking refers to the use of artificial intelligence and machine learning techniques to identify transactions or account activities that may indicate fraud. These systems analyze information associated with financial activity and generate alerts when certain patterns appear suspicious.
Traditional fraud detection often uses predefined rules. For example, a bank might flag a transaction when its value exceeds a specified threshold or when activity occurs in a pattern that violates an established security rule.
Rules are useful because they are relatively easy to understand and can identify known warning signs. However, fraud techniques change. A fixed rule may fail to recognize a new pattern, while a very broad rule may generate too many unnecessary alerts.
Machine learning adds another layer. A model can learn statistical patterns from historical transaction data and use those patterns to estimate whether new activity deserves attention.
Depending on the bank's system, machine learning may support:
Identifying unusual transaction amounts or frequencies.
Recognizing changes in customer spending behavior.
Detecting unusual account activity and transfer patterns.
Prioritizing transactions or accounts for investigation.
Identifying relationships between accounts that may indicate coordinated activity.
These systems generally support fraud monitoring and investigation. They do not independently establish that a customer has committed fraud.
2. What Information Does a Fraud Detection Model Examine?
Machine learning models depend on input features. A feature is a measurable piece of information that a model uses to produce a prediction or risk score.
In transaction monitoring, a model may examine several categories of information, subject to the bank's data access, security controls, and applicable requirements.
Transaction amount
The value of a transaction can provide useful information. A payment that is significantly larger than a customer's usual transactions may deserve additional attention. However, a large payment is not automatically fraudulent. Customers may make occasional purchases, pay fees, or transfer money for legitimate reasons.
Transaction frequency
A sudden increase in the number of transactions may be a warning signal. For example, an account that normally makes a few transfers each day may suddenly perform dozens of transfers within a short period.
Time and location patterns
Transaction timing and available location-related signals may help identify activity that differs from a customer's usual pattern. However, location data can be inaccurate, and legitimate customers may travel or use different devices.
Device and access information
Depending on the payment channel, systems may examine device identifiers, login behavior, session information, or changes in access patterns. Such information can help identify unusual account access, but it must be handled carefully because it may involve sensitive personal data.
Account and transaction history
Historical information can help a model understand what is typical for an account or a group of similar accounts. Repeated transfers, sudden changes in activity, and unusual movement of funds may provide useful signals for investigation.
No single feature is enough to establish fraud. The value comes from examining several signals together and understanding the context in which the transaction occurred.
3. How Machine Learning Identifies Suspicious Transactions
Machine learning fraud detection generally involves collecting relevant data, preparing features, training or configuring a model, and evaluating its outputs. The exact process varies between banks and payment systems.
Step 1: Collecting transaction data
The system receives transaction information through the bank's monitoring infrastructure. Depending on the application, this may include transaction amount, timestamp, account information, channel, available device signals, and relevant historical patterns.
Step 2: Preparing useful features
Raw transaction records are converted into structured features. For example, instead of examining only the value of one payment, a system may calculate how many transactions occurred during the previous hour or how much money moved through the account during a defined period.
Step 3: Applying a model
A trained model analyses the available features and produces an output. This could be a fraud-risk score, a classification, or an alert that indicates the transaction should receive additional attention.
Step 4: Applying risk thresholds and controls
The bank may use risk thresholds and additional rules to decide what action should follow. A low-risk transaction may continue normally, while a transaction with stronger warning signals may trigger additional authentication, monitoring, or investigation.
Step 5: Reviewing outcomes
Investigation results and confirmed cases can provide information for evaluating and improving the detection process. However, feedback must be checked carefully. Incorrect labels or incomplete investigation outcomes can also affect future model performance.
The important point is that a model does not simply understand fraud in the way a human investigator does. It identifies patterns based on its training data, features, and design.
4. What Is Anomaly Detection?
Anomaly detection is a technique used to identify observations that differ significantly from an expected pattern. In banking, it can help identify transactions or account activity that appear unusual compared with historical behavior or other relevant observations.
Imagine that a customer usually makes three or four digital payments in a day, with most transactions involving relatively small amounts. Suddenly, the account performs twenty transfers within a few minutes, followed by a large withdrawal.
The system may identify this activity as an anomaly because it differs from the observed pattern. It can then generate an alert for further examination.
Anomaly detection is useful because not every fraudulent activity matches a previously known fraud pattern. It can help identify unusual behavior even when a specific rule has not been written for that exact situation.
However, an anomaly is simply something unusual. It does not automatically mean something is wrong.
For example:
A customer may make several payments while shopping during a festival.
A business may receive an unusually large payment after completing a contract.
A customer may transfer money to a new account for a legitimate personal reason.
A traveller may make payments from a location that differs from their usual activity.
All these events may look unusual to a model, but they can be legitimate. This is why anomaly detection should be understood as a way of identifying activity for attention, not as a final fraud verdict.
5. A Simple Example: How a Bank Might Flag a Transaction
Consider a fictional customer named Riya. Her account usually has a predictable pattern of digital payments. Most transactions are relatively small, and she rarely transfers money to new beneficiaries.
One evening, the account performs several high-value transfers to newly added recipients within a short period. The transaction monitoring system notices that the activity differs from the customer's historical pattern.
For illustration, the system examines the following features:
Feature | Usual pattern | Current activity |
|---|---|---|
Number of transfers in 30 minutes | 1–2 | 9 |
Typical transfer amount | ₹1,500 | ₹18,000 |
New beneficiaries | Rare | Several |
Transaction timing | Spread across the day | Concentrated in a short period |
These numbers are fictional and are used only to demonstrate how transaction features can be compared.
The model may assign the activity a higher risk score because several features differ from the usual pattern. The bank's monitoring workflow may then generate an alert or apply an appropriate additional check.
But what if Riya is paying several suppliers for a legitimate purchase? What if she has just changed her usual payment behavior? The model cannot establish the full explanation from the alert alone.
A bank may need to examine additional information, apply its fraud-control procedures, and contact the customer through appropriate channels. The final response should depend on the available evidence and the bank's policies.
6. False Positives: When Legitimate Transactions Look Suspicious
A false positive occurs when a fraud detection system flags legitimate activity as suspicious. This is one of the important challenges in transaction monitoring.
Imagine a customer who usually makes small purchases. One day, the customer buys a laptop, books travel tickets, and pays a large medical bill. The combined activity differs significantly from the customer's usual pattern.
A model may interpret this change as unusual and generate an alert. However, the transactions may all be genuine.
False positives can create several problems:
Customer inconvenience: Legitimate payments may be delayed or declined while additional checks take place.
Investigation workload: Fraud teams may spend time examining transactions that are ultimately found to be legitimate.
Reduced customer confidence: Repeated unnecessary alerts can frustrate customers.
Operational costs: Banks may need additional staff and systems to manage large numbers of alerts.
There is also an opposite problem: false negatives. These occur when fraudulent activity is not flagged by the system.
A fraud detection system must therefore balance the risk of missing fraudulent transactions against the cost and inconvenience of incorrectly flagging legitimate ones.
Simply increasing the number of alerts does not necessarily make a system better. A useful system should help identify meaningful risks while keeping unnecessary interruptions manageable.
7. Why Human Review Still Matters
Machine learning can process large volumes of information quickly, but human investigators remain important in many fraud-monitoring workflows.
A model may identify an unusual pattern, assign a risk score, or prioritize an account for investigation. A trained investigator can examine the available context, check supporting information, follow established procedures, and determine what action is appropriate.
Human review is especially important when:
The transaction has a significant financial impact.
The model produces an alert based on conflicting signals.
The customer disputes a transaction or reports account misuse.
The activity involves several linked accounts.
The system's output is uncertain or the available data is incomplete.
Human review does not mean that investigators are always correct. People can also make mistakes, overlook evidence, or be influenced by assumptions. Good processes should therefore include clear investigation procedures, documented decisions, appropriate escalation, and quality checks.
The objective is to combine the speed and pattern-recognition capabilities of technology with human judgement and accountability.
8. India's Efforts to Identify Mule Accounts
A mule account is a bank account used to receive, transfer, or move money connected with fraudulent or criminal activity. In some cases, criminals recruit people to allow their accounts to be used. In other cases, accounts may be compromised or misused without the account holder's full understanding.
Mule accounts can make financial fraud harder to investigate because funds may move through several accounts before reaching their final destination.
India has taken steps to strengthen the identification of suspected mule accounts through banking supervision, transaction monitoring, intelligence sharing, and technology-led detection.
RBI's MuleHunter.AI initiative
In a Ministry of Finance press release published on 24 March 2026, the government stated that the Reserve Bank of India had rolled out MuleHunter.AI, an AI/ML-based solution for identifying mule accounts. The release reported that the solution was live in 26 banks and was being scaled up.
The same release described the use of real-time transaction monitoring, AI/ML tools, and network analytics to identify suspicious transaction patterns and mule networks. It also referred to the incorporation of the Indian Digital Payment Intelligence Corporation in October 2025, with a mandate involving technology-led detection and analysis of digital payment fraud.
Source: Ministry of Finance / Press Information Bureau, 24 March 2026.
I4C and RBI Innovation Hub collaboration
On 12 May 2026, the Ministry of Home Affairs announced that the Indian Cyber Crime Coordination Centre (I4C) and Reserve Bank Innovation Hub (RBIH) had signed a Memorandum of Understanding to strengthen cooperation against cyber-enabled financial frauds and mule accounts.
The announcement described sharing suspect-account intelligence from I4C's Suspect Registry to strengthen AI-driven fraud detection systems, including MuleHunter.ai. It also referred to the use of datasets for training and improving fraud-risk assessment models.
Source: Ministry of Home Affairs / Press Information Bureau, 12 May 2026.
These announcements show that India is using technology, banking coordination, and intelligence sharing to strengthen fraud detection. They do not mean that every suspected mule account is automatically confirmed as criminal or that AI alone resolves the problem. Investigation, appropriate action, and safeguards remain necessary.
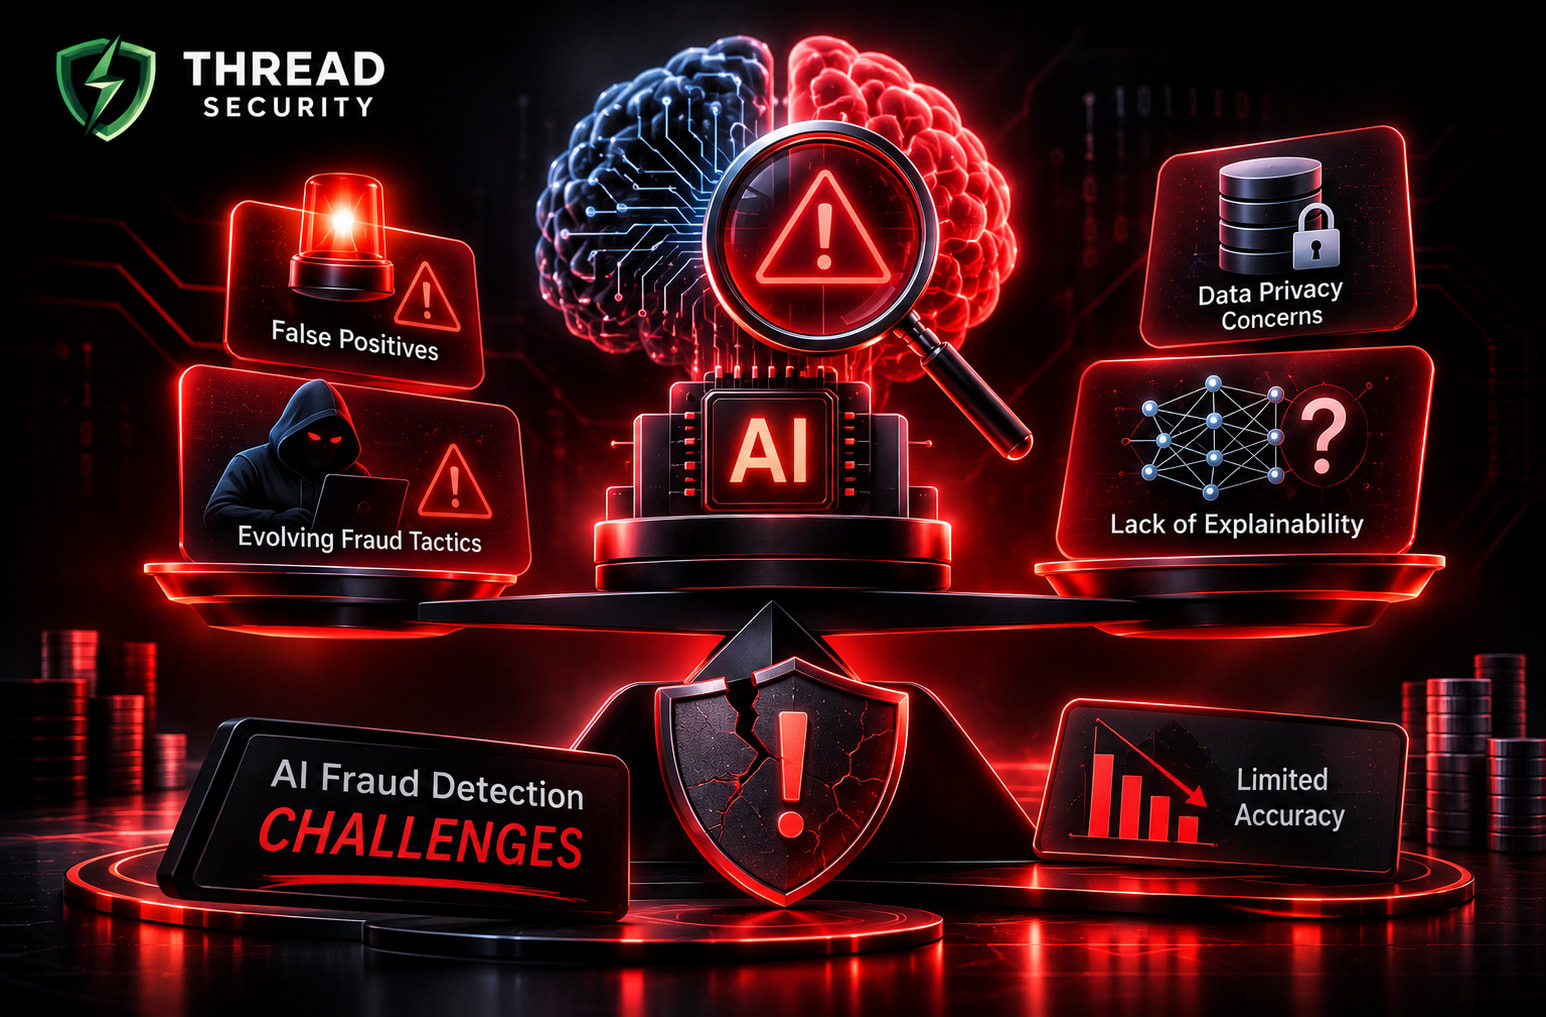
9. Challenges and Limitations of AI-Based Fraud Detection
Although machine learning can improve transaction monitoring, it is not a complete solution to financial fraud. Several practical challenges affect how well these systems perform.
Changing fraud patterns: Criminals adapt their methods, so models trained on older examples may fail to recognize new behavior.
Incomplete or inaccurate data: Missing, outdated, or incorrect information can affect model outputs.
False positives: Legitimate changes in customer behavior may trigger unnecessary alerts.
False negatives: Some fraudulent activity may resemble normal transactions and remain undetected.
Privacy and security: Transaction monitoring uses sensitive financial information that must be protected through suitable access controls and safeguards.
Model drift: Changes in customer behavior, payment methods, or fraud techniques can reduce the relevance of previously learned patterns.
Explainability: Investigators may need to understand why a model generated an alert, particularly when the consequences for a customer are significant.
Operational integration: An effective model must work with existing banking systems, investigation teams, security controls, and reporting procedures.
These limitations explain why banks need continuous monitoring, model evaluation, secure data practices, and clearly defined investigation processes.
10. How Banks Can Evaluate Fraud Detection Systems
A fraud detection model should not be evaluated only by counting how many transactions it flags. Banks need to understand how well it identifies genuine fraud, how many legitimate transactions it incorrectly flags, and how effectively alerts support investigation.
Some useful evaluation concepts include:
Precision: Of the transactions flagged as suspicious, how many were actually confirmed as fraudulent?
Recall: Of the known fraudulent transactions, how many did the model successfully identify?
False-positive rate: How frequently does the system incorrectly flag legitimate transactions?
Detection time: How quickly can suspicious activity be identified and escalated?
Investigation workload: How many alerts require manual examination, and how much effort does each investigation involve?
There is no single metric that captures the complete quality of a fraud detection system. A model with high recall may identify more fraudulent activity but also generate more false alarms. A model with high precision may generate fewer unnecessary alerts but miss some fraud cases.
Evaluation should reflect the bank's risk priorities, customer impact, transaction environment, and investigation capacity.
11. A Beginner-Friendly Learning Exercise
Students interested in machine learning and financial fraud detection can explore the concepts using a public or synthetic transaction dataset. The exercise should be designed for learning rather than making real financial decisions.
A simple project workflow could involve:
Choose a suitable anonymized or synthetic transaction dataset.
Examine features such as transaction amount, time, frequency, and transaction category.
Inspect the distribution of normal and labelled fraudulent transactions.
Prepare the dataset and handle missing values appropriately.
Train a basic classification model, such as logistic regression or a decision tree.
Evaluate the model using precision, recall, and a confusion matrix.
Explore an anomaly detection approach and compare its results with the classification model.
Identify false positives and false negatives in the test results.
Write a short report explaining the model's limitations and why human investigation would still be necessary.
One important challenge in fraud datasets is class imbalance. Fraudulent transactions may represent only a small fraction of all observations. A model that predicts every transaction as legitimate could achieve high overall accuracy while failing to detect fraud. This is why accuracy alone is not a sufficient evaluation metric.
Students should also avoid treating model predictions as evidence of criminal behavior. The purpose of the exercise is to understand pattern detection, evaluation, and responsible use of machine learning.
Frequently Asked Questions
How do banks detect suspicious transactions?
Banks use transaction rules, monitoring systems, machine learning models, and investigation procedures to identify unusual patterns. Depending on the system, they may examine transaction amounts, frequency, account history, and other relevant signals.
What is anomaly detection in banking?
Anomaly detection identifies transactions or account behavior that differs from an expected pattern. It helps generate alerts for unusual activity, but an anomaly does not automatically indicate fraud.
What is a false positive in fraud detection?
A false positive occurs when a legitimate transaction is incorrectly flagged as suspicious. It can cause payment delays, customer inconvenience, and additional investigation work.
What is a mule account?
A mule account is an account used to receive or move funds connected with fraudulent or criminal activity. Such accounts may be knowingly or unknowingly used by account holders.
Can AI prevent all banking fraud?
No. AI can help identify suspicious patterns and support faster monitoring, but it cannot guarantee that every fraudulent transaction will be detected. Criminals adapt, data can be incomplete, and models can produce incorrect results.
Why is human review important in AI fraud detection?
Human investigators can examine context, verify information, handle disputed alerts, and follow appropriate procedures. This is particularly important when an automated alert could affect a customer's access to funds or banking services.
Final Thoughts: Detection Is Only One Part of Fraud Prevention
Machine learning has become an important tool for analyzing financial transactions and identifying suspicious patterns. By examining transaction features, customer behavior, and relationships between accounts, AI-based systems can help banks prioritize activity that requires attention.
However, unusual activity is not always fraud. False positives can inconvenience genuine customers, while false negatives can allow fraudulent activity to go unnoticed. An effective approach therefore requires reliable data, appropriate model evaluation, continuous monitoring, secure information handling, and human investigation.
India's MuleHunter.AI initiative and the collaboration between I4C and RBI Innovation Hub illustrate how AI, intelligence sharing, and banking coordination are being used to address mule-account activity. These developments are important, but technology must remain part of a broader fraud-risk management process.
At Thread Security Education, we encourage learners to understand how artificial intelligence works in real-world applications, including its capabilities, limitations, and security implications. Whether you are exploring financial fraud detection, machine learning, or AI courses in Jalandhar, practical knowledge of responsible AI systems can help you develop a stronger understanding of modern technology.
Visit Thread Security to explore our learning resources and training opportunities. Build your AI knowledge, understand emerging security challenges, and learn how technology can support safer digital systems.
Simranjit Kaur
VERIFIEDAI Trainer · Thread Security
Faculty mentor & research guide at Thread Security Education.